Kauri Dairy Holdings
THE SUCCESSION CONSENT
AGRIBUSINESS · SUCCESSION · DIFFICULTY 2/5
You have ten minutes. What do you do?
Read the file
// THE SETUP
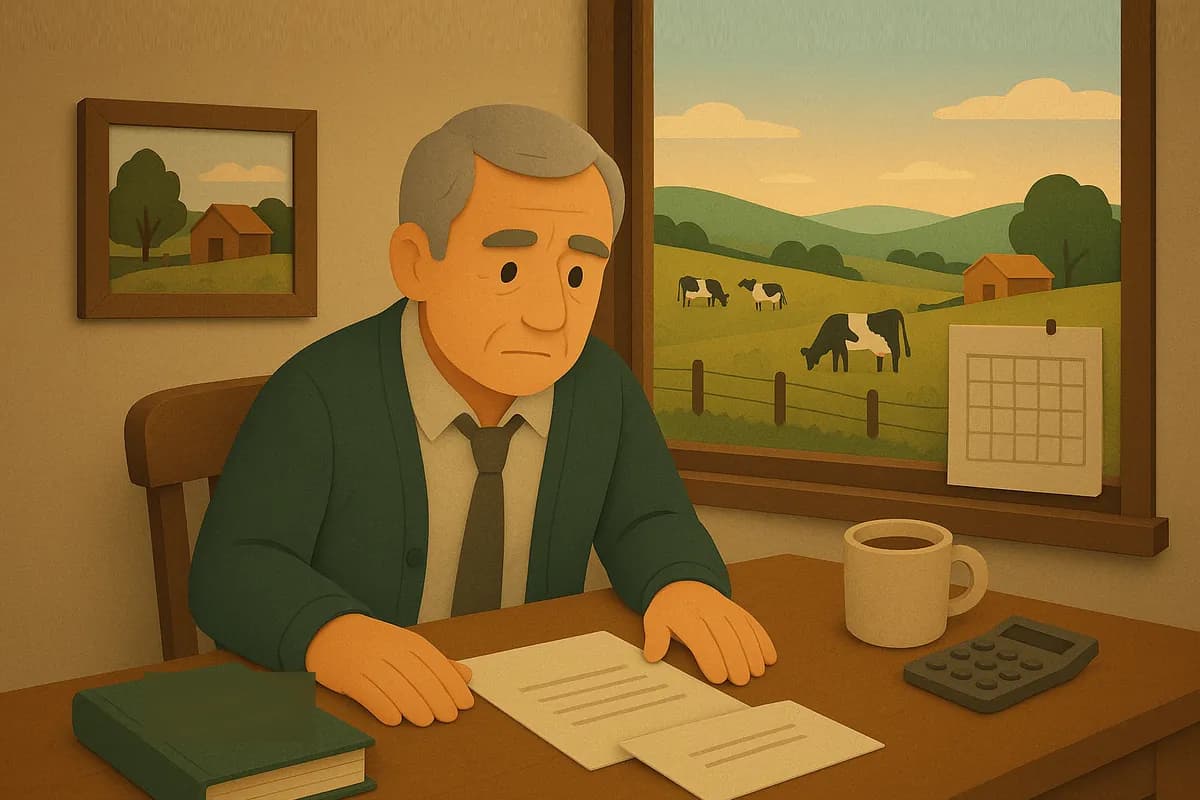
Kauri Dairy Holdings is a third-generation Waikato dairy operation — two farms, 620,000 kgMS combined, run as one business by the 68-year-old patriarch for the past thirty years. Term debt of NZ$13.0m plus a NZ$1.2m seasonal line. Conduct spotless. The payout is at a cycle high and the season just ended was the best in a decade.
On Tuesday, the family's accountant emails the relationship manager a fully drafted succession restructure: the home farm to a new entity owned by the elder son — a strong operator with a sharemilking record of his own; the second farm to an entity owned by the daughter, an Auckland professional who will keep her career and engage a sharemilker; the land into a family trust leasing back to both. The bank is asked to consent to the security reshuffle, release the patriarch's personal guarantee, and provide an additional NZ$2.0m seasonal facility for the son's entity — all before calving in August.
The patriarch has not called. The relationship manager notes, a little uneasily, that owner drawings have risen 65% over the past two years. You're on the credit committee when the consent request lands.
You have the financials. You have ten minutes. What do you do?
How a lender reads it: dairy debt is tested at a payout well below the season just paid, against each farm's own breakeven — costs, interest, repayments and drawings per kgMS.
// THE FILE
THREE YEARS OF ACCOUNTS · NZ$000 · FY23–FY25
Dairy seasons, FY25 the one just ended — the best in a decade. Milk income is kilograms of milk solids times the payout; the home farm is family-run, the second farm staff-run. Figures in NZ$000. Operating cash flow is after interest and tax paid; debtor days are on revenue, stock and creditor days on cost of sales. A composite borrower: the accounts belong to no real company.
THE FACILITIES
- Term debtFirst mortgage over both farms and the herd; the patriarch's personal guarantee over all of it.
- NOWNZ$13.0m
- REQUESTEDSplit between the two successors' entities
- Seasonal linePeaks before calving; low at the season's end.
- NOWNZ$1.2m limit
- REQUESTEDPlus NZ$2.0m for the son's new entity
- The successionAsked through the accountant, before calving in August.
- NOWOne business, run by the patriarch for thirty years
- REQUESTEDLand into a family trust, leased back; guarantee released at signing
PROFIT AND LOSS
| Line | FY23 | FY24 | FY25 |
|---|---|---|---|
| Milk income and stock sales | 5,300 | 5,026 | 5,732 |
| Farm working expenses | (2,820) | (2,900) | (2,961) |
| Gross profit | 2,480 | 2,126 | 2,771 |
| Overheads | (280) | (290) | (300) |
| EBITDA | 2,200 | 1,836 | 2,471 |
| Depreciation | (310) | (320) | (330) |
| EBIT | 1,890 | 1,516 | 2,141 |
| Interest | (870) | (880) | (892) |
| Profit before tax | 1,020 | 636 | 1,249 |
| Tax | (286) | (178) | (350) |
| Net profit after tax | 734 | 458 | 899 |
BALANCE SHEET AT YEAR-END
| Line | FY23 | FY24 | FY25 |
|---|---|---|---|
| Cash | 484 | 312 | 321 |
| Receivables | 450 | 430 | 490 |
| Inventory | 290 | 300 | 310 |
| Current assets | 1,224 | 1,042 | 1,121 |
| Land, buildings, herd and co-op shares | 26,040 | 26,020 | 25,990 |
| Total assets | 27,264 | 27,062 | 27,111 |
| Trade payables | 340 | 350 | 360 |
| Seasonal line (drawn) | 600 | 700 | 600 |
| Term debt | 13,350 | 13,100 | 13,000 |
| Total liabilities | 14,290 | 14,150 | 13,960 |
| Shareholders' equity | 12,974 | 12,912 | 13,151 |
CASH FLOW
| Line | FY23 | FY24 | FY25 |
|---|---|---|---|
| EBITDA | 2,200 | 1,836 | 2,471 |
| Increase in working capital | (10) | 20 | (60) |
| Interest paid | (870) | (880) | (892) |
| Tax paid | (286) | (178) | (350) |
| Operating cash flow | 1,034 | 798 | 1,169 |
| Capital expenditure | (350) | (300) | (300) |
| Family drawings | (400) | (520) | (660) |
| Term debt drawn / (repaid) | (200) | (250) | (100) |
| Seasonal line drawn / (repaid) | 100 | 100 | (100) |
| Net change in cash | 184 | (172) | 9 |
RATIOS FROM THE STATEMENTS ABOVE
| Ratio | FY23 | FY24 | FY25 |
|---|---|---|---|
| Revenue growth | — | -5.2% | 14.0% |
| EBITDA margin | 41.5% | 36.5% | 43.1% |
| Operating cash flow ÷ EBITDA | 47.0% | 43.5% | 47.3% |
| Debtor days (on revenue) | 31 | 31 | 31 |
| Stock days (on cost of sales) | 38 | 38 | 38 |
| Creditor days (on cost of sales) | 44 | 44 | 44 |
| Cash conversion cycle, days | 25 | 25 | 25 |
| Total debt ÷ EBITDA | 6.3× | 7.5× | 5.5× |
THE REST OF THE FILE · SECURITY · COVENANTS · CONDUCT · BUDGET
As the file stood when the accountant's email arrived: the FY25 season closed and its accounts prepared, the budget for the season ahead in hand. What a bank has on file beyond the accounts — enough to write a full credit paper on. A composite borrower: none of it belongs to a real company.
OWNERSHIP, PEOPLE, LAND
- 100% The patriarch — Every share in Kauri Dairy Holdings Ltd, and its sole director
- The patriarch.
- 68. Third generation; has run the business for thirty years and farms the home farm himself. The guarantor.
- The elder son.
- Sharemilks on his own account, off the family's farms. Not a shareholder, director or employee of the company.
- The daughter.
- Lives and works in Auckland. Not a shareholder, director or employee of the company.
- The second farm's manager.
- Employed by the company; eight seasons in the role, with two assistants.
- The accountant.
- Prepares the season accounts and the budget, and sent the succession restructure to the bank.
Both farms are freehold and both titles are in the company's name: the home farm, farmed by the family for three generations, and the second farm, the block next door but one, bought in 2011 for NZ$3.4m. The two share machinery and are run as one business. Both supply one co-operative on its standard terms and hold the co-operative shares that supply requires; milk is paid monthly on an advance rate that steps up through the season, with the balance after the season closes.
FACILITIES AND PRICING
- Term loans — three tranches
- NZ$13.0m at the FY25 year-end; NZ$13.1m a season earlierTranche A NZ$6.5m fixed at 6.20% until 2027; tranche B NZ$4.5m fixed at 6.60% until 2028; tranche C NZ$2.0m floating, 7.10% through FY25 — 6.5% across the threeInterest only, with a principal reduction agreed at each annual review and taken from tranche C: NZ$0.20m in FY23, NZ$0.25m in FY24, NZ$0.10m in FY25. Each tranche is rolled when it expires.
- Seasonal line
- Limit NZ$1.2m; NZ$0.60m drawn at the FY25 year-endFloating; 7.6% on drawings through FY25; line fee 0.40% on the limitReviewed each season. Peaks before calving; lowest late in the season.
SECURITY
- First registered mortgages, both titles
- The home farm and the second farm. Independent valuations for the bank at the FY25 year-end, land and buildings: NZ$13.1m and NZ$8.7m.
- General security agreement
- Over all the company's present and after-acquired property: the herd of 1,390 cows, the plant and machinery, and the co-operative shares.
- The patriarch's personal guarantee
- Unlimited, covering everything the company owes the bank. On the file with the mortgages since the second farm was bought.
COVENANTS, TESTED ON THE SEASON ACCOUNTS
| Covenant | FY23 | FY24 | FY25 |
|---|---|---|---|
| Interest cover (EBIT to interest) At least 1.5×, on the season accounts | 2.2× | 1.7× | 2.4× |
- Season accounts from the accountant within four months of the season's end, with a certificate of interest cover. FY25's are in the file.
- The accountant's budget for each season, before it begins.
- The land revalued for the bank every three years; last at the FY25 year-end.
- Nothing monthly or quarterly is required.
- Every interest payment and every principal reduction on its date, and the seasonal line inside its limit at every month-end on the file.
THE SEASONAL LINE, MONTH-END BY MONTH-END · LIMIT NZ$1.20m
- JunNZ$0.88m
- JulNZ$1.13m
- AugNZ$1.06m
- SepNZ$0.88m
- OctNZ$0.69m
- NovNZ$0.50m
- DecNZ$0.38m
- JanNZ$0.30m
- FebNZ$0.25m
- MarNZ$0.22m
- AprNZ$0.20m
- MayNZ$0.60m
The FY25 season. Highest at the end of July, before calving; lowest at the end of April; up again in May as winter grazing and feed are paid ahead of the dry months. No excess and no dishonoured payment in the season.
THE TWO FARMS, FY25 SEASON
- Home farmFamily-run: the patriarch, a herd manager and two farm assistants
- LAND236 ha, 214 effective
- COWS790
- kgMS350,000
- Second farmStaff-run: the farm manager and two assistants
- LAND158 ha, 142 effective
- COWS600
- kgMS270,000
- Both farms
- LAND394 ha, 356 effective
- COWS1,390
- kgMS620,000
Young stock are grazed off both farms under contract.
MILK SOLIDS BY FARM, THREE SEASONS
- Home farm
- FY23340,000
- FY24345,000
- FY25350,000
- Second farm
- FY23260,000
- FY24265,000
- FY25270,000
- Both farms, kgMS
- FY23600,000
- FY24610,000
- FY25620,000
Paid at NZ$8.20, NZ$7.60 and NZ$8.60 a kilogram in the three seasons.
THE FAMILY'S DRAWINGS
- Drawn in the season
- FY23NZ$0.40m
- FY24NZ$0.52m
- FY25NZ$0.66m
- Per kilogram of milk solids
- FY23NZ$0.67
- FY24NZ$0.85
- FY25NZ$1.06
Taken by the patriarch. The season accounts record them as one line.
THE ACCOUNTANT'S DRAFT, AS RECEIVED
- The land
- THE DRAFT PROPOSESBoth titles to the family trust, leased back to the two companies
- The home farm
- THE DRAFT PROPOSESFarmed by a new company owned by the elder son
- The second farm
- THE DRAFT PROPOSESA new company owned by the daughter, which will engage a sharemilker, not yet chosen
- Herd, plant and co-operative shares
- THE DRAFT PROPOSESFollow each farm to its company
- The NZ$13.0m of term debt
- THE DRAFT PROPOSESSplit between the two companies by production, 350:270; the trust's land mortgaged to the bank for both
- Seasonal lending
- THE DRAFT PROPOSESA further NZ$2.0m line for the son's company
- The personal guarantee
- THE DRAFT PROPOSESReleased at signing
- Timing
- THE DRAFT PROPOSESBefore calving, in August
Sent to the relationship manager by email. The leases and the trust deed are referred to, not attached.
THE ACCOUNTANT'S BUDGET FOR THE SEASON AHEAD, ONE BUSINESS
- Milk solids
- FY25 ACTUAL620,000 kgMS
- FY26 BUDGET625,000 kgMS
- Payout
- FY25 ACTUALNZ$8.60
- FY26 BUDGETNZ$8.40, the accountant's assumption
- Milk income and stock sales
- FY25 ACTUALNZ$5.73m
- FY26 BUDGETNZ$5.65m
- Farm working expenses
- FY25 ACTUALNZ$2.96m · NZ$4.78/kgMS
- FY26 BUDGETNZ$3.01m · NZ$4.82/kgMS
- EBITDA
- FY25 ACTUALNZ$2.47m
- FY26 BUDGETNZ$2.33m
- Interest
- FY25 ACTUALNZ$0.89m
- FY26 BUDGETNZ$0.89m
- Family drawings
- FY25 ACTUALNZ$0.66m
- FY26 BUDGETNZ$0.68m
- Term debt principal
- FY25 ACTUALNZ$0.10m
- FY26 BUDGETNZ$0.10m
- Capital spending
- FY25 ACTUALNZ$0.30m
- FY26 BUDGETNZ$0.32m
- Seasonal line at the season's end
- FY25 ACTUALNZ$0.60m
- FY26 BUDGETNZ$0.57m, peaking near NZ$1.15m before calving
LAST YEAR'S BUDGET, AGAINST WHAT ARRIVED
| Line | BUDGET | ACTUAL |
|---|---|---|
| Payout | NZ$7.90 | NZ$8.60 |
| Milk solids, kgMS | 615,000 | 620,000 |
| Farm working expenses | NZ$2.94m | NZ$2.96m |
| Family drawings | NZ$0.60m | NZ$0.66m |
WHAT IS STILL NOT IN THE FILE
A real file would also hold these. A paper that says which of them it needs before approving, and why, is reading the file properly.
- The family trust's deed: its trustees, its beneficiaries, and what it says about the land.
- The two leases the draft refers to: the rent, the term, and who maintains what.
- A sharemilking agreement for the second farm. The sharemilker has not been chosen.
- A current statement of the guarantor's own assets and liabilities, outside the company.
- Both farms' resource consents for effluent and water, and when each comes up for renewal.
With the rest of the file above, this one is complete enough for a full credit paper. Write one, and the first three sent in are read free, the way the senior reads here are written — how the pilot works.
// YOUR JUDGMENT
What do you do with this request?
The Lab
One case file and one question, in your inbox every Tuesday morning, New Zealand time. The senior banker's read opens only after you answer.
FREE WITH IT · ANNOTATED PDF
A complete credit paper on a published file, with the approver's notes on what each section has to answer.